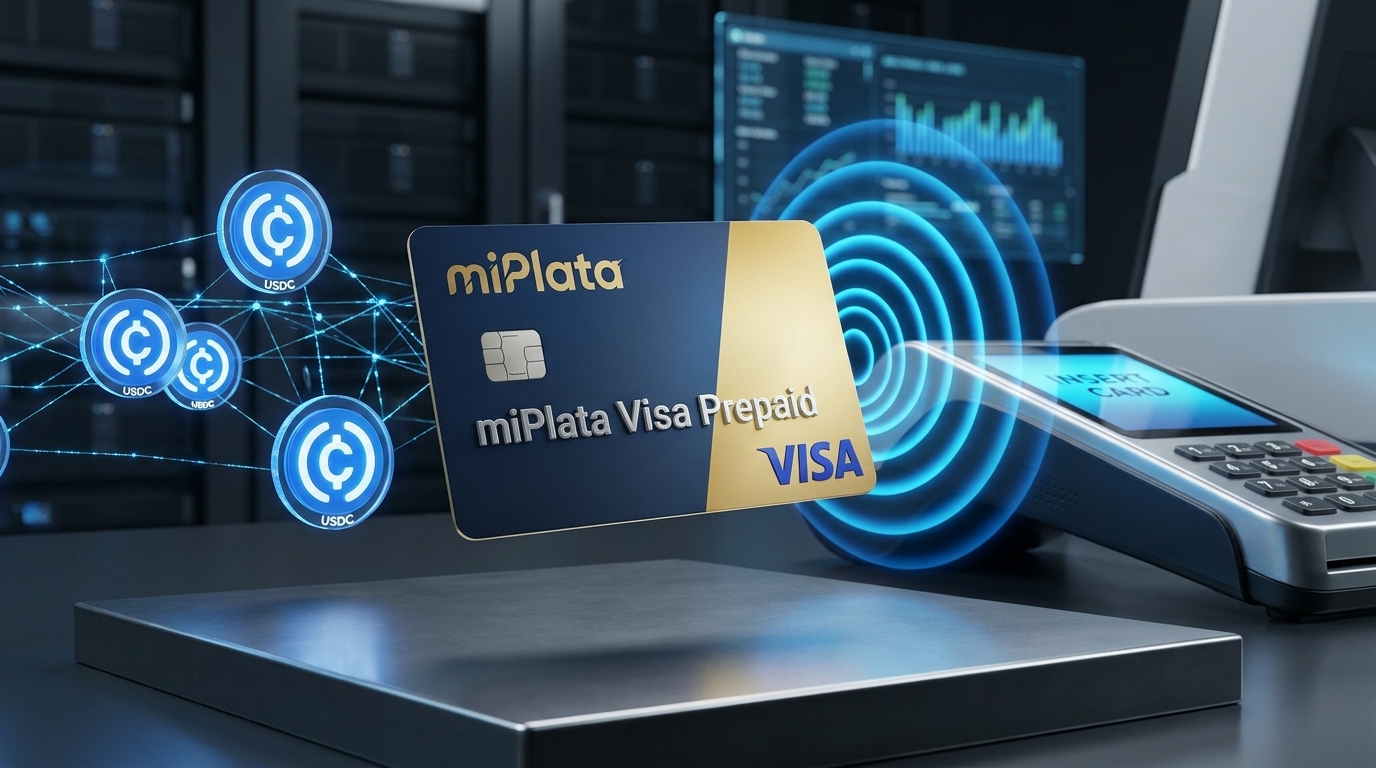
Stablecoins are moving beyond crypto trading and into everyday spending. miPlata, a financial technology platform serving Latino workers and families, has launched a physical Visa prepaid card that allows users to spend directly from their stablecoin balances without first cashing out to a bank account.
Stripe Crypto announced the launch on November 9, saying miPlata used Stripe Issuing to develop the card in just five weeks. The service allows customers to make payments anywhere Visa is accepted, connecting their digital dollar balances to the existing card payment network.
The launch offers another example of how payment companies are making stablecoins more practical for everyday transactions, particularly for people who receive digital payments or move money across borders.
How the miPlata Visa card works
The prepaid card connects spending to a user’s stablecoin balance. Instead of withdrawing funds to a traditional bank account before making a purchase, eligible miPlata customers can use the card to pay at merchants that accept Visa.
Stablecoins are cryptocurrencies designed to maintain a relatively stable value, often by tracking a currency such as the US dollar. USDC, issued by Circle, is one example. Unlike Bitcoin, whose market price can rise or fall significantly, a dollar-pegged stablecoin is designed to maintain a value close to $1.
miPlata has previously referred to a USDC card in its project updates. However, Stripe’s latest announcement did not identify every stablecoin supported by the new card, so the full list of eligible assets remains unclear.
The card also does not require merchants to accept cryptocurrency directly. Payments are processed through Visa’s existing network, allowing customers to use the card at participating merchants without requiring businesses to maintain crypto wallets.
Stripe said it supported the launch by handling the card’s identification setup, Visa approval process, production and delivery.
Why miPlata is targeting Latino workers and families
miPlata describes itself as a stablecoin-powered wallet for Latino workers and families. Its services focus on financial tools such as digital accounts, payroll and transfers to Latin America.
For people who receive money digitally or send funds to relatives in another country, having a way to spend stablecoin balances directly could reduce the number of steps involved in accessing their money.
For example, a user who receives funds in a supported stablecoin may be able to use the card for everyday purchases instead of first transferring the balance to a bank account.
Whether this approach saves money will depend on the card’s fees, exchange rates and conversion costs. Stripe and miPlata have not publicly detailed all those charges in the launch announcement.
The card’s availability, supported countries, spending limits and full list of eligible stablecoins also remain unclear.
Stripe expands its stablecoin payment infrastructure
The miPlata launch builds on Stripe’s wider effort to connect stablecoins with familiar financial services.
Stripe Issuing allows businesses to create and manage payment cards through its infrastructure. Its stablecoin-related services, alongside its Bridge business, are helping fintech companies build products that connect blockchain-based balances with established payment networks.
This can reduce the technical and operational work involved in launching a card programme. Instead of independently arranging card production, network approvals and payment infrastructure, a fintech can use existing services to bring a product to market more quickly.
Stripe’s announcement that miPlata developed the card in five weeks highlights how payment infrastructure providers are trying to shorten the time required to launch financial products.
The approach also gives fintech companies a way to offer stablecoin spending without asking customers to learn how to use a crypto exchange every time they want to make a purchase.
What this means for stablecoin adoption
Stablecoins have become widely used in cryptocurrency trading and digital asset transfers. Their role in payments is also growing as businesses explore ways to move dollar-denominated value across borders.
A stablecoin-linked Visa card brings that use case closer to everyday shopping. Customers can hold supported digital assets while using a payment card at familiar retail outlets.
However, the card does not eliminate every challenge associated with stablecoins. Users still need to understand applicable fees, account eligibility, conversion arrangements and the risks associated with the service provider and the underlying digital asset.
Stablecoins are also not the same as insured bank deposits, and protections can differ depending on the product and its legal structure.
For miPlata, the launch adds a new spending option to its financial services. For Stripe, it demonstrates how its infrastructure can help connect stablecoin balances to established payment networks.
The next test will be whether customers adopt the card for regular spending and whether the service can offer a practical, cost-effective alternative to existing ways of accessing and transferring money.
Read also: ShinyHunters stole 335 million Binance user records, demands $900,000