Paying with cryptocurrency is possible in thousands of places online, but using it to buy a phone, pay for a meal, or shop in a physical store is still less common than paying with a bank card. The difficulty is not simply getting digital assets from one wallet to another. Businesses also need a way to process those payments, manage price fluctuations, and receive money in a currency they can use.
Ezeebit is building the infrastructure to make that possible for African merchants. The South African fintech connects cryptocurrency wallets to retail and e-commerce payment systems, allowing customers to pay with digital assets while merchants receive settlement in local currency or stablecoins.
Founded by brothers Daniel Katz, David Katz, and Jonathan Katz, Ezeebit combines blockchain payments, automated currency conversion, merchant tools, and compliance infrastructure. Its aim is to make crypto payments work within existing commercial systems rather than requiring businesses to build their own cryptocurrency operations.
How Ezeebit started
Ezeebit was founded in 2022, with the company describing its operations as beginning in 2023. The three co-founders are Daniel Katz, the chief executive officer; Jonathan Katz, the chief operating officer; and David Katz, who leads financial operations. The company is headquartered in Cape Town, South Africa.
The founders’ interest in the business came from the difficulties involved in moving money across borders and the limitations of traditional payment systems for businesses operating in African markets.
Their idea was to build a payment layer that could connect digital assets to ordinary commerce. Rather than asking every retailer to learn how cryptocurrency works, manage private keys, or monitor token prices, Ezeebit would handle those processes in the background.
The company has since developed infrastructure for physical stores, online merchants, and platforms that want to integrate crypto payments directly into their products.
How Ezeebit works
Ezeebit’s payment process connects three parties: the customer making a payment, the merchant receiving it, and the infrastructure that processes the digital asset transaction.
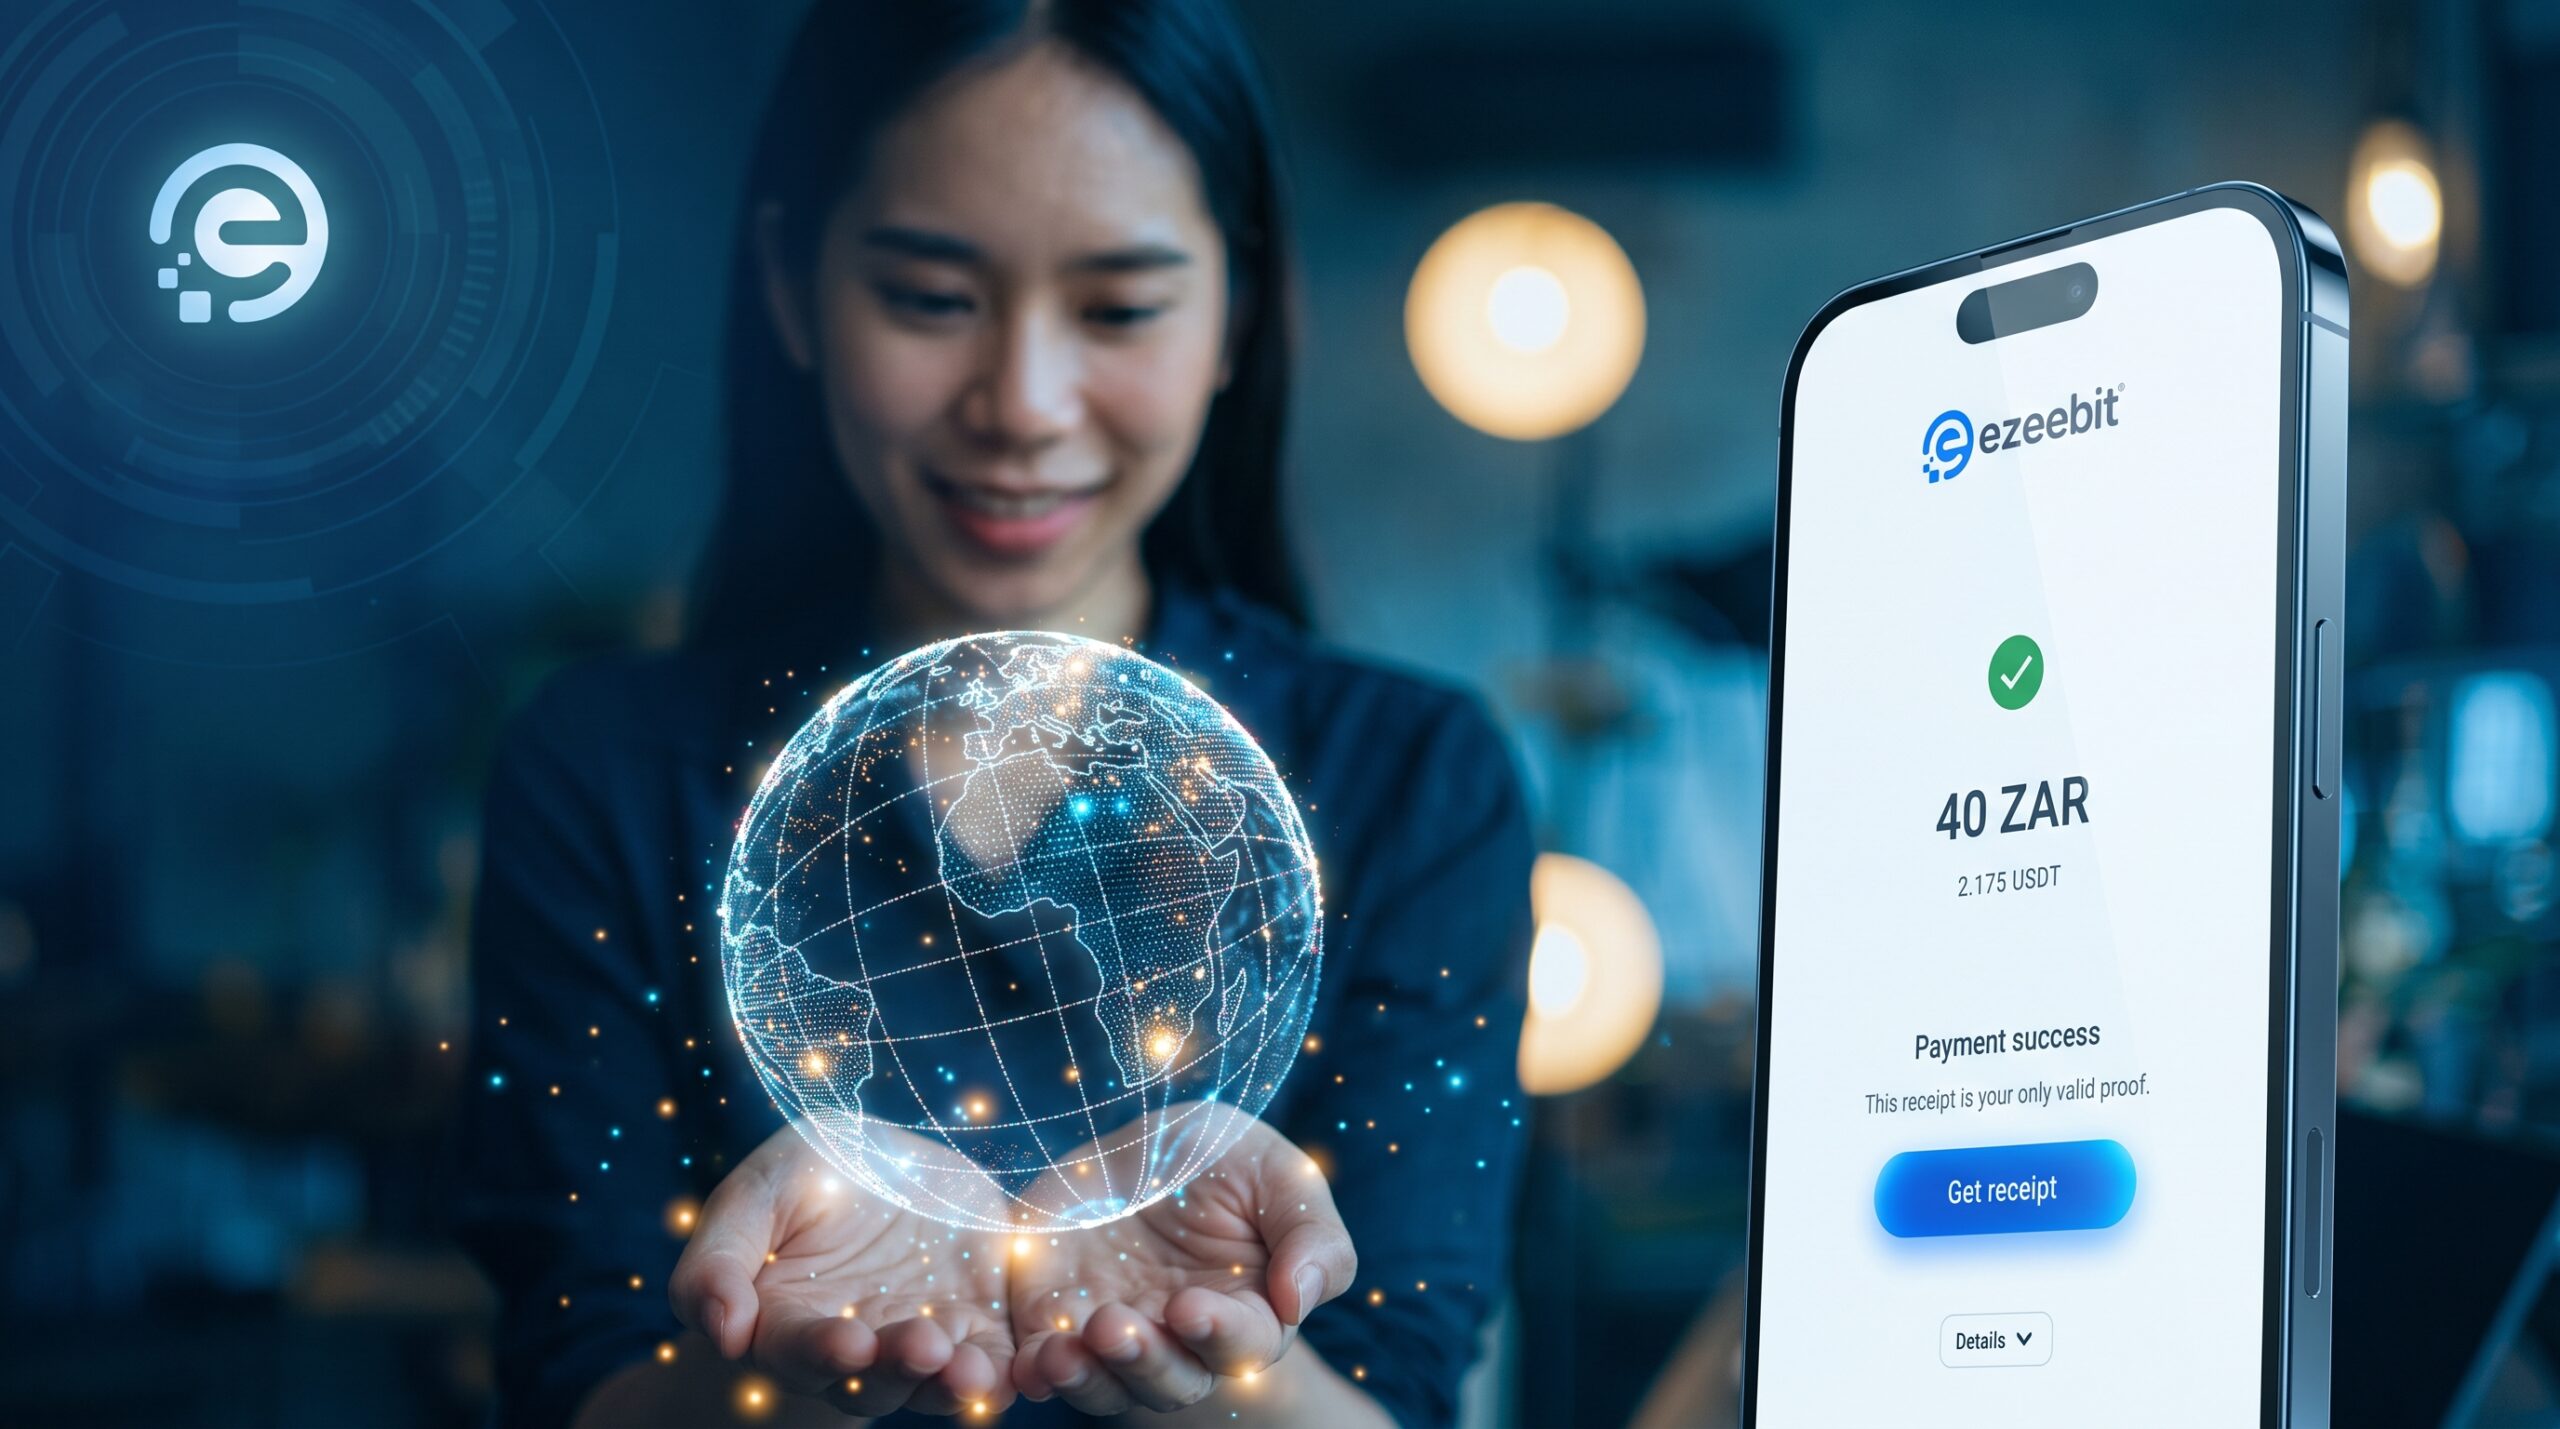
A customer can pay using a supported cryptocurrency or stablecoin from a compatible wallet. Ezeebit processes the payment, confirms the transaction, locks the exchange rate, and manages conversion and hedging before settling the funds with the merchant.
The merchant can choose to receive local fiat currency or supported stablecoins. Ezeebit lists South African rand, Kenyan shillings, and Nigerian naira among its settlement options, with availability depending on the relevant market and payment arrangement. Fiat settlement is generally offered on a next-business-day basis, while stablecoin settlement can provide access to funds more quickly.
This separation between the customer’s payment method and the merchant’s settlement currency is central to the product.
A customer may prefer to spend USDT or Bitcoin, while a retailer may want to receive rand directly into its bank account. Ezeebit handles the technical and financial processes connecting those two preferences.
Supporting multiple cryptocurrencies and wallets
Ezeebit supports several major digital assets, including Bitcoin (BTC), Ether (ETH), Tether (USDT), USD Coin (USDC), BNB, and other supported cryptocurrencies.
Customers can pay directly from compatible blockchain wallets or connect through WalletConnect, which lets users link supported wallets to payment applications. Ezeebit also advertises direct integrations with platforms such as Luno, VALR, and Binance, giving customers additional ways to make payments. Its website lists compatibility with more than 700 wallets through its supported payment connections.
This wallet-agnostic approach means customers do not necessarily need to open a new wallet specifically for shopping with Ezeebit merchants.
The platform’s role is to connect existing digital asset holdings to a merchant’s checkout process. For businesses, that can make crypto acceptance available to a wider group of customers without requiring the business to support every wallet or blockchain integration independently.
Stablecoin settlement and price protection
Cryptocurrency prices can change rapidly. A retailer that agrees to accept a payment worth R1,000 could receive a different value if the asset’s price changes before conversion or settlement.
Ezeebit addresses this through rate locking and automated hedging. According to its product documentation, the exchange rate is locked when a payment is made, and its treasury manages the conversion and hedging process. The company says this process is designed to avoid leaving merchants exposed to cryptocurrency price movements between payment and settlement.
Stablecoins are important to this model because they are designed to maintain a relatively stable value against a reference asset, usually a fiat currency such as the US dollar.
For example, a customer could pay with USDT, while a merchant receives the corresponding value in rand. Alternatively, the merchant could choose to receive USDT or USDC instead of local currency.
The merchant does not have to keep the cryptocurrency received from the customer or manage its price fluctuations directly. Ezeebit handles the conversion and settlement process through its infrastructure.
This makes the platform useful for businesses that want to accept digital asset payments without taking on the operational responsibility of managing a crypto portfolio.
Point-of-sale systems and online checkout
Ezeebit supports cryptocurrency payments in physical retail environments as well as online stores.
For physical merchants, the company offers point-of-sale payment capabilities that allow customers to pay with supported digital assets at checkout. This brings blockchain-based payments into the same commercial environment where customers already use cards and other electronic payment methods.
For online businesses, Ezeebit provides payment integrations, APIs, and e-commerce connectivity. Merchants can incorporate crypto acceptance into their checkout processes rather than directing customers to an unrelated service to complete a payment.
The company also supports integrations for businesses that need more customised payment flows. These include platforms that want to accept deposits, process payments, or connect digital asset transactions to their existing applications.
The distinction matters because crypto payments are not limited to retail purchases. The same infrastructure can support e-commerce platforms, marketplaces, fintech applications, and other businesses whose customers want to use digital assets.
APIs for businesses and fintech platforms
Beyond its retail payment product, Ezeebit provides APIs that developers can use to integrate cryptocurrency payments into their own systems.
The APIs support payment processing and related merchant operations, while webhooks allow an integrated application to receive updates about payment activity. Ezeebit also provides a sandbox environment so businesses can test integrations before launching them in production.
This gives the company a role beyond that of a point-of-sale provider.
A fintech platform could use Ezeebit to accept crypto deposits. An online marketplace could offer digital asset payments to customers. A business operating across several countries could integrate the service into its payment flow and connect it to its existing settlement processes.
Ezeebit’s embedded wallet infrastructure also supports its broader approach to digital asset payments. Combined with its APIs, these tools allow businesses to incorporate blockchain-based payment functions without developing every component independently.
The company is therefore building for both individual merchants that need a ready-to-use payment solution and technology businesses that want to integrate crypto payments into their own products.
Connecting Web3 with traditional finance
Ezeebit’s Web3 connection lies in the way it links blockchain networks and self-custodied digital assets with conventional merchant payment systems.
On the customer side, payments can originate from cryptocurrency wallets and move across supported blockchain networks. On the merchant side, the business can receive fiat currency through familiar banking channels or retain value in supported stablecoins.
The platform sits between these two environments, handling transaction processing, conversion, settlement, and related operational controls.
This is an example of payment infrastructure connecting Web3 with existing financial services. The merchant does not need to operate a decentralised application or manage blockchain transactions directly, while the customer can use digital assets already held in a compatible wallet.
Ezeebit also highlights compliance and security as part of its infrastructure. The company lists Financial Sector Conduct Authority-related registration, Financial Intelligence Centre compliance, customer and business verification, anti-money laundering controls, and MPC wallet technology among its security and compliance features.
Multi-party computation, or MPC, is a method of managing cryptographic keys in which key control is distributed rather than concentrated in a single location. It is used in digital asset security systems to reduce the risks associated with a single point of failure.
These controls are relevant to businesses that want to accept digital assets while maintaining the procedures expected of a payment service provider. The exact regulatory requirements still depend on the market and the services being provided.
Merchant adoption and retail partnerships
Ezeebit’s infrastructure is already being used in South African retail. Its merchant network includes brands such as iStore, Le Creuset, Diesel, and Amiri, among other businesses. The company has reported more than 150 participating stores and over 100,000 transactions processed.
These integrations demonstrate how crypto payments can be introduced into conventional retail without requiring each merchant to build a separate blockchain payment system.
Ezeebit also promotes transaction fees of around 1%, excluding VAT, and says blockchain payments can avoid conventional card chargebacks because confirmed on-chain transactions are generally irreversible. Actual fees depend on the merchant’s arrangement, and refunds must still be handled through an appropriate process.
For merchants, the appeal is the possibility of reaching customers who hold cryptocurrency while keeping payment operations close to their existing workflows.
For customers, the service offers another way to spend digital assets on goods and services instead of limiting their use to exchanges, trading platforms, or Web3 applications.
Funding and expansion across Africa
In December 2025, Ezeebit announced a $2.05 million seed funding round led by Founder Collective and Raba Partnership, with additional participation from strategic investors. The funding was intended to support product development, merchant growth, and expansion into markets including Kenya and Nigeria.
The company has continued developing its payment infrastructure for African businesses, with its product offering supporting settlement in rand, Kenyan shillings, and Nigerian naira where available.
In 2026, Ezeebit also expanded its connections to the regional digital asset ecosystem through an integration with ZARU, a rand-backed digital asset. The integration allows participating merchants to accept ZARU through Ezeebit’s payment infrastructure, connecting a digital representation of the rand to existing retail checkout and settlement systems.
This is a notable development because it brings a locally denominated digital asset into a merchant payment environment. Rather than relying exclusively on dollar-linked stablecoins, such integrations can support the use of digital assets representing local currencies.
Ezeebit’s expansion plans reflect the wider opportunity to connect digital asset payments with local banking and retail infrastructure. Its progress will depend on developing more merchant relationships, expanding payment routes, and meeting the regulatory requirements of each market it enters.
The role Ezeebit could play in everyday crypto use
Cryptocurrency adoption is often discussed in terms of trading, investment, and decentralised finance. But using digital assets for ordinary payments requires a different set of systems, including merchant checkout tools, reliable conversion, settlement options, and compliance controls.
Ezeebit is focused on this practical layer of the digital asset economy. It connects crypto wallets to physical stores, online businesses, and fintech platforms, while handling the processes that allow merchants to receive value in a usable form.
Its combination of point-of-sale technology, payment APIs, wallet integrations, stablecoin settlement, and treasury-managed conversion gives businesses a way to accept digital assets without managing the entire blockchain payment process themselves.
The larger opportunity is to make cryptocurrency useful beyond the platforms where it is bought and traded. If Ezeebit continues expanding its merchant network and payment integrations across African markets, it could help connect more digital asset holders with the businesses they already use.
Ultimately, Ezeebit’s value will be measured not simply by how many merchants enable crypto payments, but by how reliably those payments work in everyday commerce. Its infrastructure is designed to make the blockchain activity largely invisible to the merchant, leaving customers free to pay with digital assets and businesses free to focus on serving them.